

Subscription Stopper & Manager
3.9

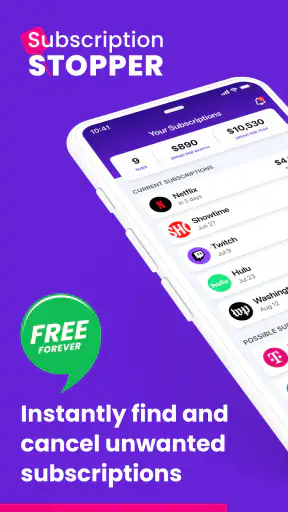
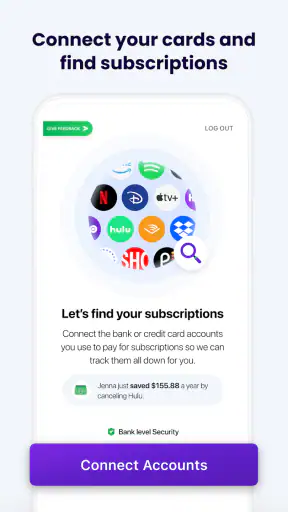
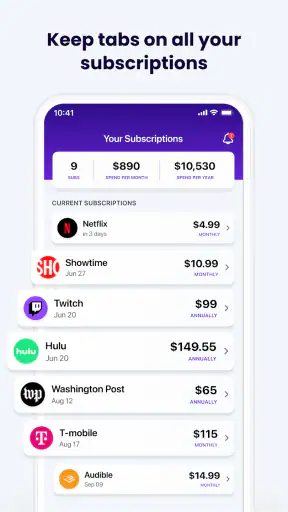
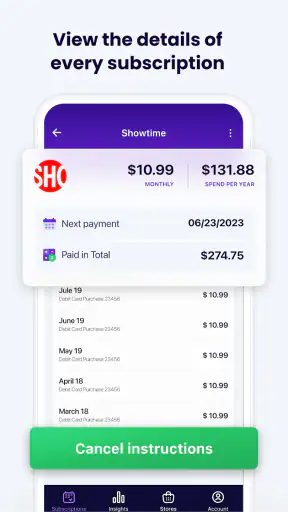
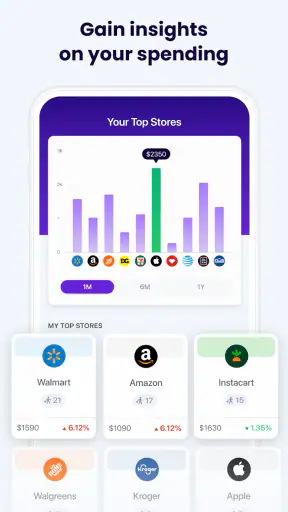
Keeping track of recurring charges sounds simple until several services renew at different times, some are billed through an app store, and others are paid directly on a website. Subscription Stopper & Manager is designed for that particular problem: it combines subscription management, bill tracking, and basic budgeting in one finance app. I found its appeal less in flashy presentation and more in the way it encourages a person to look at recurring spending as a regular household task rather than something to remember only after a charge appears.
The app is developed by InMarket Media, LLC and is available free of charge, with optional in-app purchases ranging from $5.99 to $99.00 per item. It is rated for Everyone, runs on Android 7.0 or later, and its current version is 2.0.8. With an average rating of 3.9 from around 3.6 thousand ratings, it has attracted more than 100 thousand installs. Those figures suggest a useful but not universally loved tool, which matches my impression: it can be helpful when you want visibility and reminders, but it is not a complete replacement for careful checking of your bank and service accounts.
What I would check before choosing it
My first decision criterion would be the kind of problem you are trying to solve. If you regularly forget which services renew, want to identify recurring bills, or need a simple place to review monthly commitments, this app is aimed at you. If you are looking for a full banking dashboard, detailed investment analysis, or an advanced envelope-budgeting system, I would look elsewhere. Its purpose is narrower, and that focus is part of its usefulness.
I would also ask how much manual organization I am willing to do. Any subscription manager is only as useful as the information it contains. Even when an app helps identify recurring expenses, I still need to check names, renewal timing, and amounts. A service may appear under a payment processor rather than the brand I recognize, and a yearly plan can be easy to overlook if I think only in monthly terms. The best results come from treating the first setup as an audit, not as a quick installation.
Privacy and control are important decision points too. A finance app can make money management more convenient, but I would not connect or enter anything without first understanding what the app asks me to provide and how comfortable I am with that arrangement. For someone who prefers to keep every financial detail in a spreadsheet, a dedicated subscription tool may feel unnecessary. For someone who wants a guided overview, the convenience may justify the extra step.
The final criterion is whether the app helps me take action. A list of recurring charges is useful, but the real value comes from deciding what to keep, what to cancel, and what to renegotiate. I would judge the app by how quickly it helps me reach those decisions, not simply by how many entries it displays.
A practical first session
My recommended starting point is to gather recent bank or card statements before opening the app. I would scan for repeating charges, write down the service name and billing interval, and then use the app to organize the results. This prevents a common mistake: assuming that the first screen contains every subscription automatically. A careful first pass also makes unfamiliar merchant names easier to identify.
After entering or reviewing the list, I would separate essential services from occasional conveniences. Streaming, cloud storage, fitness memberships, software tools, delivery programs, and trial offers often feel harmless individually, but their combined renewal schedule can be surprisingly difficult to remember. I would then check the next expected billing date for each one and create a short cancellation plan rather than trying to deal with every service at once.
One useful habit is to review the list immediately after a major life change. Moving, changing jobs, sharing a household, or switching schools can make old subscriptions less relevant. The app works best as a recurring checkpoint: I would open it before a monthly budget review and again before a period when annual renewals are likely to appear. That workflow turns a passive list into a decision tool.
Where Subscription Stopper & Manager wins
The strongest part of this app is its clear focus on recurring commitments. Many traditional budgeting apps place subscriptions alongside groceries, transport, utilities, and one-time purchases. That broad view is useful, but it can hide the specific expenses that quietly continue every month. Here, the central question is more direct: which services are still taking money, and do I still want them?
I also like the combination of subscription management and bill tracking. These are related but not identical tasks. A subscription is usually a repeating service decision, while a bill may be a necessary household payment that needs monitoring rather than cancellation. Keeping both ideas together makes sense for a user who wants to understand fixed monthly obligations before planning flexible spending.
The budgeting angle adds another practical layer. I would not treat it as a replacement for a full financial plan, but it can help show how recurring commitments shape the money left for everything else. That is especially useful for people who build a budget from the top down: first recurring charges, then essential bills, then savings and discretionary spending. Seeing the fixed portion first can make later choices more realistic.
The most valuable insight is not the cancellation button; it is the recurring-cost audit that comes before it. When I review a subscription list, I can notice duplicate services, overlapping benefits, and plans I kept because cancellation felt inconvenient. That awareness is harder to get from a normal banking transaction feed, where each charge appears separately and disappears into a long history.
Useful workflows beyond the obvious list
A good workflow is to use the app before a free trial ends, but not to rely on memory alone. I would record the service as soon as I start the trial, then check the app during my weekly money review. This is a small change, yet it addresses one of the most expensive subscription mistakes: forgetting that a trial is about to become a paid plan.
Another useful approach is to compare the cost of convenience with actual use. For each service, I would note the last time I used it and whether another subscription already covers the same need. This is particularly helpful for entertainment and productivity tools, where several services can perform similar jobs. The app can organize the commitments, while the decision still comes from my habits.
I would also use it to prepare a cancellation session. Rather than cancelling whenever I notice a charge, I would group nonessential services into one review, confirm which account or email controls each one, and then handle them one by one. This reduces the chance of cancelling the wrong plan or assuming that deleting an app ends a subscription. The financial record and the service account are not always the same thing, so I would verify completion separately.
For shared households, the app may be most useful as a conversation starter. One person can recognize the charge while another controls the account, and recurring services can remain active simply because nobody knows who is responsible. A monthly review of the list can turn that confusion into a short set of decisions: keep, transfer, downgrade, or cancel.
What the ratings and free entry point mean in practice
The 3.9 average tells me to approach the app with reasonable expectations rather than assuming it will perfectly identify every financial commitment. A finance tool can be valuable even when it needs checking, but users who expect complete automation may become frustrated if they have to correct entries or confirm details.
The free starting price is a meaningful advantage for trying the workflow without committing immediately. At the same time, the presence of optional purchases means I would pay attention during setup and before choosing any paid feature. I would first determine whether the free experience solves my main problem, then decide whether an upgrade offers enough convenience to justify its cost. The broad purchase range makes that comparison especially important for people who only need a simple reminder list.
The Everyone age rating also makes the app approachable for a wide household audience. Still, age suitability does not remove the need for financial judgment. I would show younger users how to recognize recurring charges and where to confirm a cancellation, rather than letting the app become an excuse to approve changes without understanding them.
Where other approaches may fit better
The usual alternative is a bank or card statement. That option has one major strength: it shows what actually reached the account. For a person who distrusts categorization or wants the most direct record of spending, the bank app may be better. Its weakness is that transactions are historical. It may not make upcoming renewals, duplicate services, or cancellation priorities easy to see.
A spreadsheet is another strong alternative. I can create columns for service, amount, billing cycle, renewal date, account owner, and cancellation status. This gives me complete control and avoids learning another interface. The trade-off is maintenance. If I forget to update one row after a price change or cancellation, the sheet slowly becomes unreliable. Subscription Stopper & Manager is more appealing when I value a ready-made structure over total customization.
Full budgeting applications may be a better choice for people who need categories, savings goals, debt tracking, or a detailed monthly plan. They usually treat subscriptions as one part of a larger financial picture. I would choose that route if recurring charges are only a small part of my concern. I would choose this app instead when subscriptions are the specific leak I want to find first.
Calendar reminders can work surprisingly well for a small number of services. I could add a reminder before each renewal and avoid installing a finance app. That method is simple, but it does not naturally provide a consolidated view of recurring spending. It also depends on me knowing every renewal date in advance. The app has a clearer advantage once the list becomes difficult to maintain manually.
Cancellation services or direct customer support can be preferable when a subscription is difficult to end, involves a dispute, or requires account verification. I would not assume that a management app can override a provider’s cancellation process. In those situations, I would use the app to identify the commitment and then complete the cancellation through the service that owns the account.
Who should skip it
I would skip this app if I have only one or two recurring services and already monitor them successfully through my bank and calendar. The extra layer would not save enough time. I would also skip it if I want detailed investment tools, tax preparation, debt payoff planning, or a highly configurable zero-based budget. Those needs go beyond the app’s subscription-centered purpose.
People who expect every charge to be recognized without review should be cautious as well. Merchant descriptions can be confusing, billing cycles can vary, and some payments may not look like subscriptions at first glance. I would rather spend a little time verifying the list than trust an automated label that could lead me to overlook an important bill or cancel the wrong service.
Finally, users who are uncomfortable placing financial information in a third-party app may prefer a local spreadsheet or their bank’s own tools. Convenience is not the only consideration in finance. If the setup creates more concern than clarity, the simpler alternative is the better choice.
The real cost of switching to it
Switching from a spreadsheet, bank app, or scattered reminders has a setup cost. I would need to identify recurring charges, match them to the correct services, and decide how to handle annual plans. That work cannot be avoided completely because no tool can decide whether I still value a subscription. The app can make the process more organized, but it cannot replace the judgment behind each decision.
There is also a learning cost. I would spend time understanding which parts of the app are free, which options involve purchases, and how the app presents bills versus subscriptions. For a person already comfortable with a spreadsheet, that may feel like unnecessary friction. For someone whose current system is a pile of emails and forgotten calendar alerts, the same setup may feel like a major improvement.
The biggest switching benefit is continuity. Once the list is accurate, I have a single place to revisit recurring commitments instead of searching through statements, inbox messages, and app-store pages. I would still keep confirmation emails and check my bank after cancelling, but the app can serve as the central checklist that prevents unfinished tasks.
My advice is to test it with a limited group of subscriptions first. I would add the services I know best, review how the information is organized, and only then expand to less familiar charges. This staged approach lowers the risk of building a large, inaccurate list and makes it easier to decide whether the app genuinely fits my routine.
An everyday example
Imagine I notice that my monthly budget feels tighter even though my major bills have not changed. I open the app and review recurring commitments rather than scanning every transaction. I find an entertainment service I rarely use, a productivity plan that overlaps with another tool, and a yearly membership I had mentally treated as a one-time payment. I do not cancel everything immediately. I check who uses each service, confirm the account details, and mark the ones that need action.
After making those decisions, I return to the app during the next budget review. The important result is not merely that I removed a few charges. I now know which renewals deserve attention, which services are shared, and which annual payments need to be planned for ahead of time. That is the kind of practical clarity this app can provide when I use it deliberately.
My recommendation after weighing the trade-offs
I recommend Subscription Stopper & Manager to people whose main financial frustration is recurring spending they cannot easily see or remember. It is especially suitable for anyone managing several digital services, a household with shared accounts, or a budget that has become crowded with small automatic payments. The free entry point makes it reasonable to try, provided I review any optional purchase carefully.
I would not present it as a complete personal-finance system. Its value is concentrated: it helps me organize subscriptions and bills so I can make better decisions. For detailed budgeting, investments, debt, or highly customized tracking, I would pair it with a stronger finance tool or choose a different category altogether.
My final advice is to use it as an audit and planning companion, not as an unquestioned financial authority. Verify unfamiliar charges, confirm cancellations with the original provider, and review the list at a regular interval. Used that way, Subscription Stopper & Manager can turn recurring expenses from background noise into a manageable checklist. That focused purpose is enough for me to recommend it, but only to users who want subscription control rather than an all-in-one banking replacement.
For my own decision, the balance is positive: the app offers a more focused view than a normal transaction history and less maintenance than building a detailed spreadsheet from scratch. Its limitations matter, especially the need for verification and the possibility that paid options may not suit every budget. Still, if forgotten renewals are the problem I am trying to solve, this is a practical place to begin.
3.9
2.13K Reviews
Pros
- Tracks recurring subscriptions in one organized dashboard.
- Helps identify forgotten services and potential monthly savings.
- Provides renewal reminders to reduce unexpected charges.
- Simple interface makes subscription details easy to review.
- Useful overview of spending across multiple subscription services.
Cons
- Some features may require manual entry or account updates.
- It may not detect every subscription automatically.
- Reminder accuracy depends on keeping billing dates current.
- Limited value for users with only a few recurring payments.
- Privacy-conscious users may hesitate to enter financial details.


